Why is my HOA going up in NorthPark and Tesoro, and what does fire insurance have to do with home affordability in Valencia?
If your HOA dues in NorthPark or Tesoro have jumped recently, fire insurance is likely the biggest reason. California’s wildfire insurance crisis is reshaping the true cost of homeownership across Valencia, Stevenson Ranch, Saugus, Canyon Country, and Newhall, and it is hitting HOA communities especially hard.
Why Fire Insurance in Valencia Matters Right Now
I get this question constantly. Homeowners in NorthPark are opening their monthly HOA statements and seeing numbers that are noticeably higher than they were even a year ago. When they call their HOA board, the answer keeps coming back to the same thing: the community’s master fire insurance policy got significantly more expensive, and that cost flows directly into your dues.
This is not a NorthPark-only issue. It is playing out across every HOA-governed community in the Santa Clarita Valley, from [Tesoro del Valle](https://timothyatwood.com/search/Tesoro del Valle) to the hilltop tracts of Stevenson Ranch. According to California Department of Insurance data, average homeowners insurance premiums across the state rose 84% between the end of 2020 and March 2026, per CDI reporting. On top of that, Californians could see rates increase another 16% by the end of 2026, per industry projections tied to insurer recovery from the 2025 wildfire season. If you are buying, selling, or simply budgeting in this market, understanding how fire insurance ripples through your HOA and your monthly affordability picture is no longer optional. It is essential.
How Fire Insurance Is Driving Up HOA Dues in NorthPark and Tesoro
Here is how it works, and I explain this to my clients regularly because most people do not realize the connection until the bill arrives.
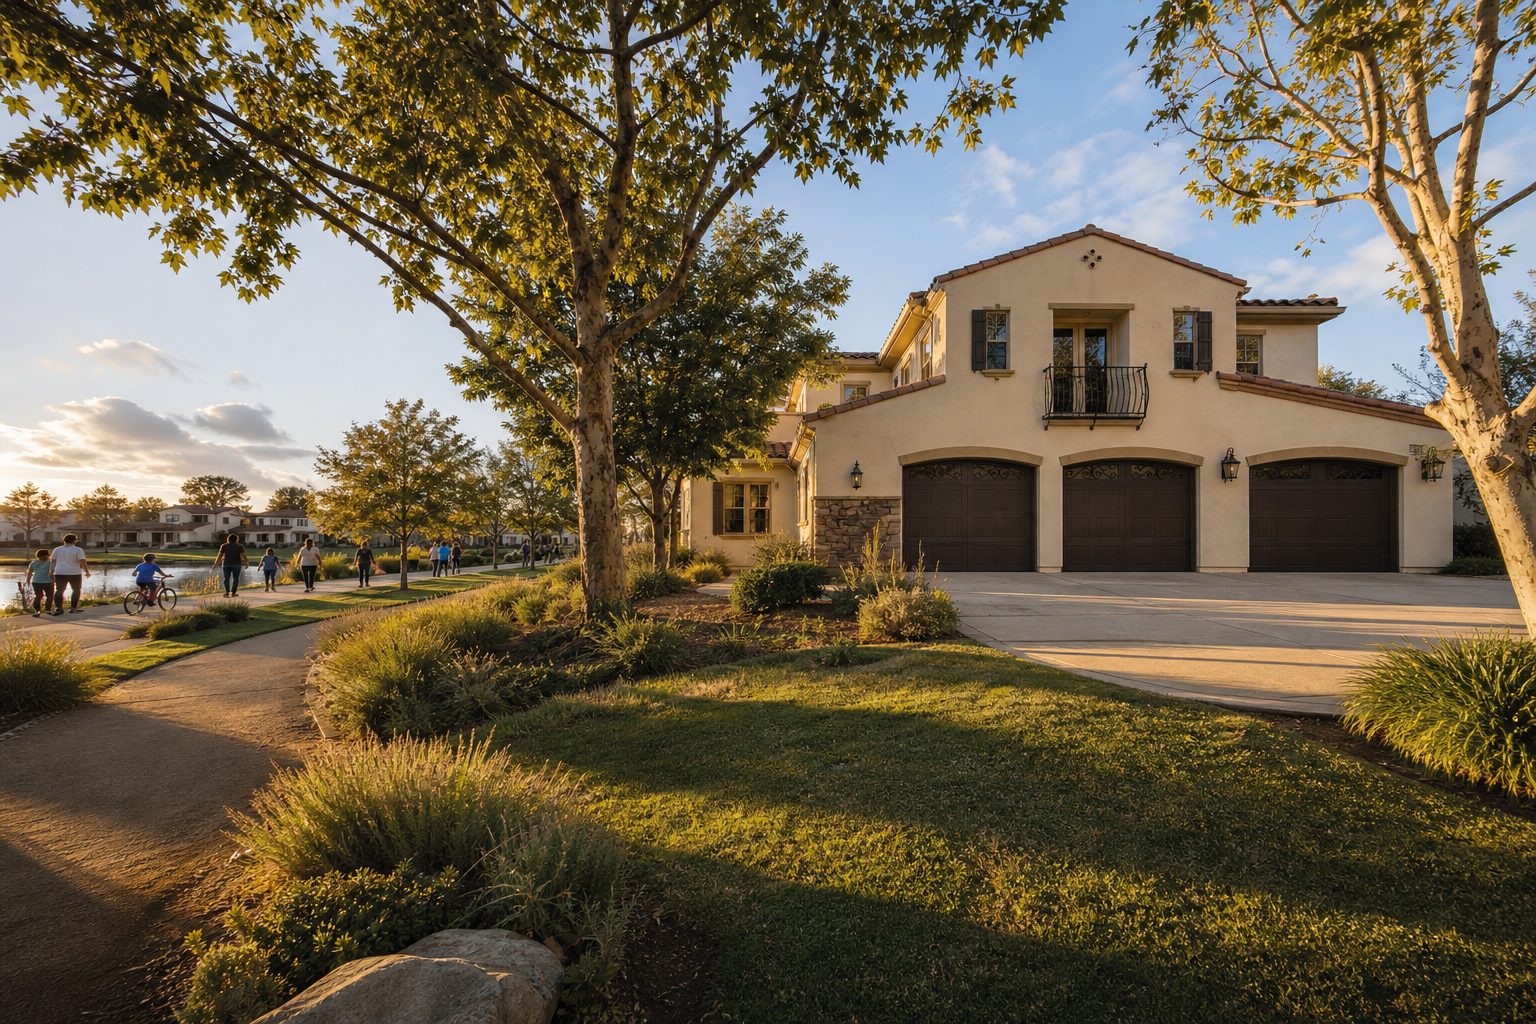
Your HOA carries what is called a master insurance policy. This policy covers common areas, shared structures, landscaping, community amenities like the Northpark Community Center and Sports Park off [Copper Hill](https://timothyatwood.com/search/Copper Hill) Drive, and in many cases, the exterior structures of homes within the association. When insurers raise premiums on that master policy, or when the HOA’s carrier drops them entirely and they are forced onto the state’s FAIR Plan (which offers only basic fire coverage at a premium price), the board has two choices: raise dues or levy a special assessment.
What I tell my clients is this: in a community like Tesoro del Valle, where entry-level condos and townhomes start closer to $475,000 to $550,000 according to recent market data, a $100 to $200 monthly HOA increase can meaningfully shift the math for a first-time buyer or someone stretching to get into Valencia. That is not a trivial amount when median monthly owner costs with a mortgage already run approximately $3,309 in this area, per Census data.
What Your HOA Insurance Actually Covers
Before you assume you are being overcharged, ask your HOA board for a breakdown. In many NorthPark and Tesoro communities, your dues now include:
- Master fire insurance covering shared structures and common areas
- Liability coverage for community amenities (pools, parks, sports courts)
- Potentially a DIC policy (Difference in Conditions), which fills gaps when the FAIR Plan is the only available fire coverage
If your HOA is absorbing a master fire insurance policy, you may actually be getting fire coverage you did not realize was baked into your monthly payment. That is worth understanding before you shop for your own individual homeowner’s policy, because there could be overlap.
How Fire Insurance Affects Single Family Home Affordability in the Santa Clarita Valley
So what about detached single-family homes where you do not have an HOA handling your fire insurance? The affordability impact is just as real, but it hits your personal budget directly.
With 12 years of experience in this market and over 62 closed transactions in the Santa Clarita area, I have watched the insurance line item go from an afterthought to one of the largest moving pieces in a buyer’s affordability calculation. Consider the total monthly cost picture for a luxury buyer in Valencia’s Northbridge, where the median sale price reached $1.1M (up 25.1% year over year, per recent market data):
- Mortgage payment at the current 30-year fixed rate of 6.67%, per Freddie Mac PMMS as of August 2026
- Property taxes including Mello-Roos, which is significant in newer Valencia and Stevenson Ranch developments
- Fire insurance, which is now the fastest-growing component of ownership costs in the SCV
FAIR Plan enrollment surged 43% between September 2024 and December 2025, per CDI data. More than one in 17 new California home loans is now being written with the most limited, most expensive coverage option as the only available choice. That statistic alone should tell you how dramatically the landscape has shifted.
What Luxury Buyers in Stevenson Ranch and Valencia Need to Ask Before Purchasing
If you are shopping in NorthPark, Tesoro, Northbridge, or Stevenson Ranch, here is the due diligence checklist I walk through with every buyer:
- Is the HOA on the voluntary insurance market or the FAIR Plan? This distinction matters enormously. FAIR Plan coverage is bare-bones and expensive.
- What is the HOA’s reserve fund situation? Adequate reserves buffer against special assessments when insurance costs spike.
- Has the HOA levied any special assessments in the last three years related to insurance? This tells you whether the board has been proactive or reactive.
- What fire zone classification applies to the property? Proximity to wildland-urban interface, which is relevant for hillside communities throughout Stevenson Ranch and upper Saugus, directly affects individual policy pricing.
- Has the homeowner completed any wildfire mitigation improvements? A CDI-commissioned study found that rebuilding to wildfire-prepared home standards could reduce projected wildfire losses by one-third on average. Carriers like CSAA now offer a 12.5% hardening discount as of 2026.
With 21 five-star reviews from past clients, I take pride in making sure buyers understand these details before they are locked into a purchase. This is the kind of guidance that separates a smooth transaction from a costly surprise.
Legislative Relief and What It Could Mean for NorthPark and Tesoro Homeowners
California’s legislature is actively working to ease the pressure. Here is what is on the table as of 2026:
- Assembly Bill 1354 proposes a tax credit for homeowners whose fire insurance premiums exceed their 2023 baseline, beginning in 2026
- AB 567 seeks to suspend the gross premiums tax on residential property policies for four years starting in 2026
- SB 1076 (Insurance Coverage for Fire-Safe Homes Act) would require insurers to offer and renew coverage to any homeowner meeting CDI wildfire safety standards
- SB 547 (Business Insurance Protection Act) extends post-fire non-renewal protections specifically to HOAs, condominium associations, and affordable housing units
For buyers in HOA communities along McBean Parkway, Copper Hill Drive, and the Tesoro corridor, SB 547 is particularly significant. It means your HOA cannot simply be dropped by its carrier without the protections that individual homeowners receive.
There is also a proposed public wildfire insurance program that would have all homeowners pay into a shared pool, guaranteeing universal coverage for catastrophic blazes. The state estimates it would require around $25 billion in investment. Whether it passes or not, the direction is clear: fire insurance is being treated as a systemic issue, not just an individual homeowner problem.
How This Shapes the Market in Saugus, Canyon Country, and Newhall
The fire insurance conversation does not stop at Valencia’s borders. Across the broader Santa Clarita Valley, the median sale price for single-family homes was $860,000 in July 2026 (down 4% year over year, per local MLS data). The market currently sits at roughly 3.7 months of inventory, approaching a more balanced state.
What I find interesting is that home prices in California have dropped about 4.3%, with steeper declines in high-fire-risk areas, per industry analysis. Canyon Country and parts of Saugus, where some neighborhoods sit closer to the wildland-urban interface, may feel this pressure more acutely than the paseo-connected streets of NorthPark. If you are comparing communities, fire insurance cost should be part of your neighborhood comparison, just like school ratings and commute times.
Frequently Asked Questions
Why did my HOA dues go up in NorthPark Valencia?
Many NorthPark HOAs now carry master fire insurance policies that cover common areas and shared structures. As California insurance premiums have risen 84% since 2020, per CDI data through March 2026, those costs are passed through to homeowners via higher monthly dues. Ask your board for a specific insurance line-item breakdown.
Does my HOA fire insurance replace my personal homeowner’s policy in Tesoro?
No. Your HOA’s master policy typically covers common areas and exterior structures, not your personal belongings or interior finishes. You still need an individual HO-6 or homeowner’s policy, but understanding what the HOA covers helps you avoid paying for duplicate fire coverage.
How much has fire insurance increased in Valencia CA?
Average California homeowners insurance premiums rose 84% between the end of 2020 and March 2026, per CDI reporting. An additional 16% average increase is projected by the end of 2026 as insurers recover from the 2025 wildfire season.
What is the FAIR Plan and does it affect Santa Clarita homeowners?
The FAIR Plan is California’s insurer of last resort, offering basic fire coverage at higher premiums. FAIR Plan enrollment surged 43% between September 2024 and December 2025, per CDI data. If your HOA or individual home is placed on the FAIR Plan, expect higher costs and more limited coverage.
Can wildfire mitigation lower my insurance premiums in Stevenson Ranch?
Yes. A CDI-commissioned study found that building to wildfire-prepared home standards could reduce projected losses by one-third on average. CSAA offers a 12.5% My Home Hardening discount as of 2026, and Travelers has expanded its mitigation discounts as well.
Are there tax credits for high fire insurance premiums in California?
Assembly Bill 1354 proposes a tax credit for homeowners whose premiums exceed their 2023 baseline, beginning in 2026. AB 567 also seeks to suspend the gross premiums tax on residential property policies for four years. Both are pending legislative action.
How does fire insurance affect home values in Canyon Country and Saugus?
Home prices in California have dropped about 4.3% broadly, with steeper declines in high-fire-risk areas, per industry analysis. Communities closer to the wildland-urban interface in Canyon Country and upper Saugus may see more pricing pressure than lower-risk neighborhoods.
What should I ask my HOA board about insurance before buying in NorthPark?
Ask whether the HOA is on the voluntary market or the FAIR Plan, what the master policy covers, what the reserve fund balance is, and whether any special assessments related to insurance have been levied in the past three years. These answers directly impact your true cost of ownership.
Does SB 547 protect my HOA from losing insurance coverage?
Yes. The Business Insurance Protection Act (SB 547) extends post-fire non-renewal protections to HOAs, condominium associations, and affordable housing units. This means your HOA’s carrier cannot simply drop coverage without the same consumer protections that apply to individual policies.
Is a public wildfire insurance program coming to California?
A proposed public wildfire insurance program would pool premiums from all homeowners to guarantee universal coverage for catastrophic blazes. The state estimates it would need around $25 billion in investment. The proposal is still being evaluated but signals the severity of the crisis.
The Bottom Line
Fire insurance is no longer a background line item in your budget. Whether you are buying a townhome in Tesoro, a family home near the Northpark Community Center, or a luxury estate in Stevenson Ranch, insurance costs are reshaping what you actually pay each month. If your HOA dues are climbing, fire insurance is almost certainly why. If you are purchasing a detached home, your individual premium deserves the same scrutiny as your mortgage rate.
With over 12 years specializing in Valencia, Stevenson Ranch, Saugus, Canyon Country, and Newhall, I help buyers navigate exactly these issues before they become expensive surprises. If you want a clear picture of what fire insurance means for a specific property or community you are considering, contact me at 213-598-8205 or visit timothyatwood.com. I am Timothy Atwood with Park Regency Realty, and I would rather have this conversation before you make an offer than after.