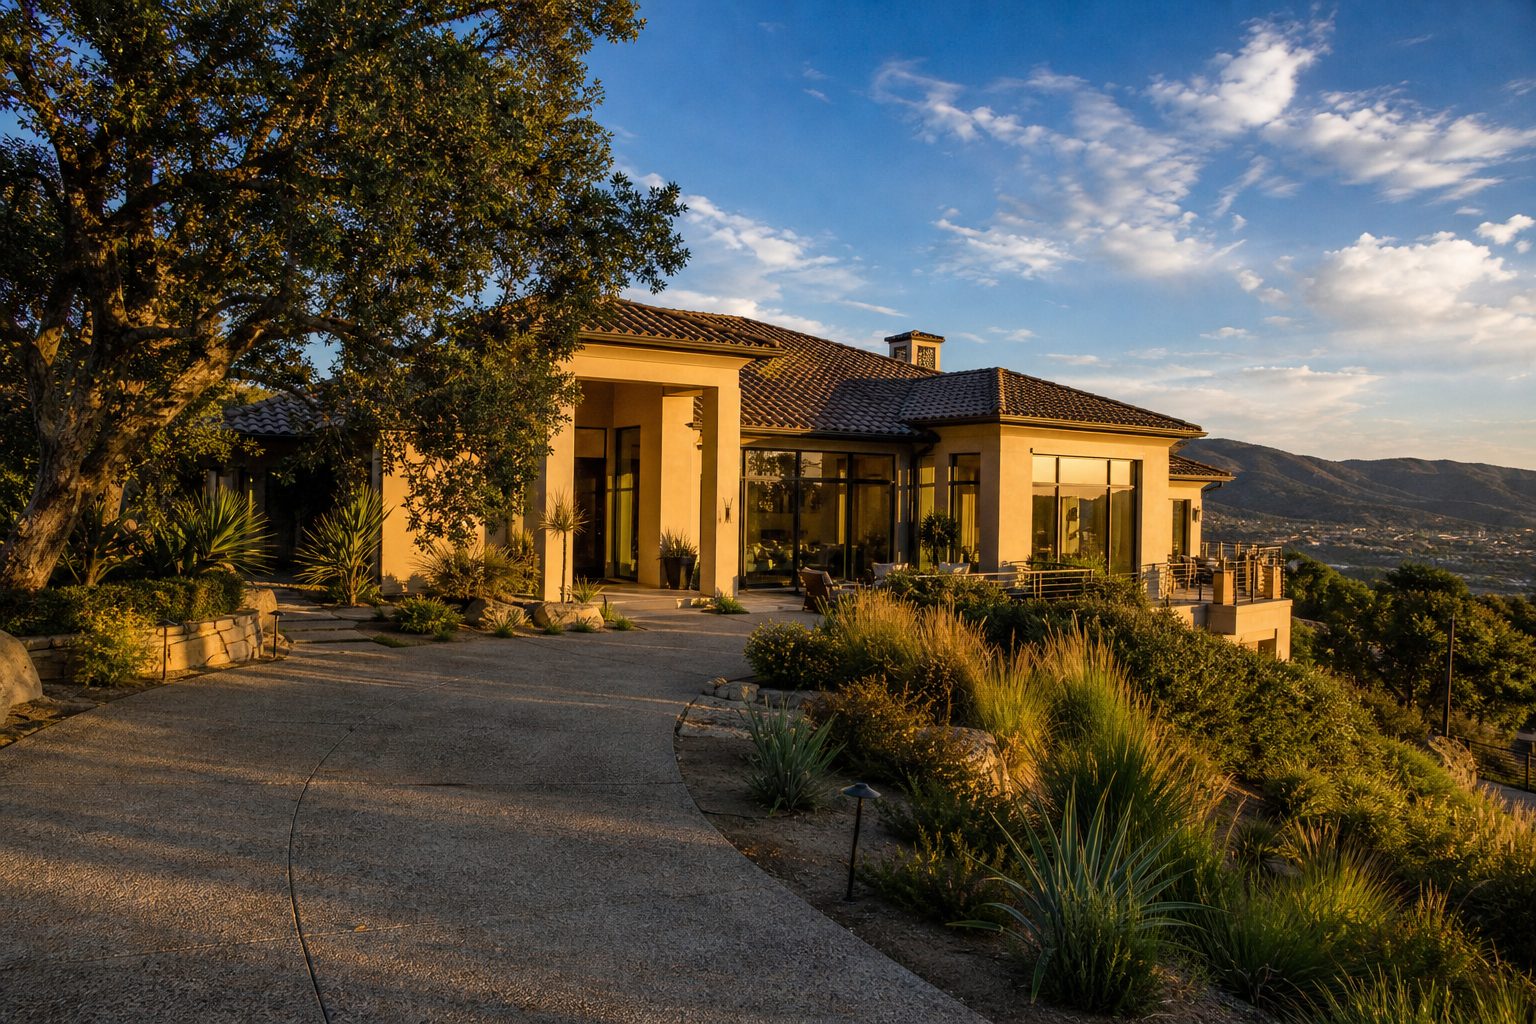
How much should you expect to pay for fire insurance on a luxury home in Valencia or Saugus?
For upscale homes in Valencia and Saugus with dwelling values between $1M and $2M, you can expect to pay roughly $3,500 to $8,500 annually in 2026, according to current California insurance market data. Homes valued above $2M can run $5,000 to $25,000 or more.
Why Fire Insurance in Valencia and Saugus Matters Right Now
I live here in the Santa Clarita Valley, and I’ve been hearing some interesting things lately about what homeowners and buyers are dealing with on the insurance front. The conversations at neighborhood gatherings, at the coffee shop off McBean Parkway, even after church, keep circling back to the same question: “What is this going to cost me?”
Here’s the context. In early 2025, the Palisades and Eaton fires caused roughly $41 billion in insured losses, per Claims Journal reporting. That single event reshaped how every carrier in California prices wildfire risk. Major insurers stopped writing new homeowners policies in high-risk zones entirely. The California FAIR Plan, the state’s insurer of last resort, saw its residential policy count increase 151% between September 2022 and March 2026, according to California Department of Insurance data, while its total risk exposure jumped 234% to $700 billion.
So what does that mean when you’re shopping for a luxury home in [Tesoro del Valle](https://timothyatwood.com/search/Tesoro del Valle), Northbridge, or the hillside pockets of Saugus? It means fire insurance is no longer an afterthought. It’s a front-and-center budget item that can swing your monthly carrying costs by hundreds, even thousands, of dollars.
What Valencia and Saugus Luxury Homeowners Are Actually Paying in 2026
Let me break this down into the ranges that matter for this market. These figures come from 2026 California insurance market analyses.
Standard homes ($500K to $800K dwelling value) in suburban LA areas like the Valencia flatlands:
- $1,400 to $2,800 per year with admitted market carriers
Upscale homes ($1M to $2M dwelling value) in moderate Fire Hazard Severity Zones:
- $3,500 to $8,500 per year
High-value and custom luxury homes ($2M to $5M dwelling value):
- $5,000 to $25,000 per year, with substantial surcharges depending on your specific wildfire zone designation
Ultra-luxury and custom builds ($5M+ rebuild cost):
- $15,000 to $60,000 per year, depending on mitigation measures and coverage structure
What does that translate to monthly? If you’re purchasing in Northbridge, where the median home price hit $1.1M as of 2026 market data (up 25.1% year-over-year), your insurance might add $290 to $710 per month on top of your mortgage, taxes, and HOA. That’s a meaningful number. With 12 years of experience helping buyers navigate this market and 62 closed transactions under my belt, I can tell you that most people don’t budget for this until it’s too late in the process.
How Your Specific Location in Valencia or Saugus Changes the Price
Here’s something most buyers don’t realize until they’re deep into escrow: not all of Valencia and Saugus carry the same fire risk classification. Your premium is driven by your wildfire and brush score, dwelling rebuild cost, roof type, distance to fire protection, deductible structure, and claims history, per California insurance industry data. Carriers rate each factor independently, and the combined effect can swing your premium by 5x to 20x for the same dwelling value.
Most of the Valencia and Saugus flatland areas are NOT in Very High Fire Hazard Severity Zones, which keeps premiums more moderate than hillside communities. But here’s where it gets nuanced:
- Tesoro del Valle, Valencia’s premier luxury pocket with homes ranging from $1.0M to $1.5M+, sits at higher elevation along the ridgeline above Avenida Rancho Tesoro. That hillside positioning, while beautiful, can push your fire risk classification higher.
- Saugus hillside homes near the Placerita Canyon corridor carry different risk profiles than the flatland neighborhoods closer to Bouquet Canyon Road.
- Bridgeport and West Creek, by contrast, sit in the Valencia flatlands near Bridgeport Lake and benefit from proximity to fire stations and hydrant infrastructure, typically keeping premiums on the lower end of the range.
What I tell my clients is this: before you fall in love with a property, get an insurance quote. Not after the inspection. Not during escrow. Before you even write an offer.
The FAIR Plan: What Valencia and Saugus Luxury Buyers Need to Know
If you cannot find coverage through a standard (admitted) carrier, the California FAIR Plan becomes your fallback. But it has significant limitations for luxury homeowners.
The FAIR Plan caps residential coverage at $3 million, per the California FAIR Plan’s current policy limits. For many luxury homes in the Santa Clarita Valley, particularly new construction from builders like Toll Brothers at Tesoro Highlands (where homes start from $1,719,000 for the Bella Terra Collection and $1,899,000 for Alta Monte, per 2026 builder pricing), a $3 million cap might cover the rebuild. But for custom luxury homes where rebuild costs run $475 to $700 per square foot (or $650 to $1,100+ per square foot for true custom builds, according to Claims Journal data from July 2026), that cap can leave you significantly underinsured.
The FAIR Plan also only covers fire losses. You need a separate policy for everything else: theft, liability, water damage, personal property.
The typical FAIR Plan cost structure, per 2026 data:
- Average California dwelling: $3,000 to $3,200 per year
- $400,000 dwelling in a Very High Fire Hazard Severity Zone: $3,200 to $4,800 per year
- $1 million dwelling in a foothill county: $5,000 to $9,000 per year
For luxury homeowners, the standard approach is to layer a Difference in Conditions (DIC) policy on top of the FAIR Plan. This combination approximates the scope of admitted market coverage but typically costs 1.5x to 2.5x what an admitted policy would run. For a $1M dwelling in a high-fire zone, that total FAIR Plan plus DIC cost can reach $9,500 to $15,000 annually, per 2026 insurance industry estimates.
Specialty Carriers for High-Value Homes in the Santa Clarita Valley
If you’re purchasing at the luxury level, you have options beyond the standard market. Carriers like Chubb, PURE Insurance, AIG Private Client Group, and Cincinnati Insurance specialize in high-net-worth coverage and offer benefits standard carriers simply don’t provide: guaranteed replacement cost, extended coverage, and concierge claims service.
Chubb, for reference, runs approximately $3,200 per year for a standard $300K dwelling, per 2026 rate data. It’s premium-priced, but for a $2M+ home in Valencia or Saugus, the guaranteed replacement cost feature alone can be worth the premium difference.
Rated 5 out of 5 stars by 21 past clients, I’ve walked buyers through this exact decision point many times. The right carrier depends on your home’s specific characteristics, your risk tolerance, and whether you value claims service speed over upfront premium savings.
How to Reduce Your Fire Insurance Costs in Valencia and Saugus
You’re not powerless here. Several factors are within your control, and they can meaningfully shift your premium.
- Construction materials matter. Fire-resistant construction like stucco or brick can reduce premiums to $1,000 to $2,200 per year versus $1,500 to $3,000 for standard wood frame, per 2026 California insurance data.
- Defensible space and sprinkler systems can earn a 10% to 25% discount from many carriers.
- Distance to a wildfire zone is a major factor. Homes within 5 miles of a wildfire zone see a 20% to 50% premium increase, per industry data.
- Your deductible structure is a lever. A higher deductible means lower premiums, but make sure you can absorb that cost if the worst happens.
- Bundling and loyalty discounts still apply with many admitted carriers and specialty insurers.
As someone who holds the Rising Star Award and the Rookie of the Year distinction from my brokerage, I’ve made it a priority over my career to understand these details. Real estate isn’t just about finding the right house. It’s about making sure you can afford to protect it.
Pros and Cons of Fire Insurance Options for Valencia and Saugus Luxury Buyers
Choosing the right fire insurance structure is not one-size-fits-all. Here is a straightforward breakdown to help you weigh your options.
Admitted Market Carriers (e.g., Chubb, PURE Insurance)
Pros:
- Comprehensive coverage in a single policy
- Guaranteed replacement cost available
- Concierge claims service for high-value properties
- Generally the most straightforward coverage structure
Cons:
- Increasingly difficult to obtain in hillside and brush-adjacent areas
- Premiums have risen significantly since the 2025 fires
- Some carriers have paused new policy issuance in high-risk ZIP codes
California FAIR Plan Only
Pros:
- Available as a last resort when admitted carriers decline coverage
- Residential cap of $3 million covers many standard luxury rebuilds
Cons:
- Covers fire losses only — no theft, liability, water damage, or personal property
- $3 million cap may be insufficient for custom luxury homes with rebuild costs of $475 to $1,100+ per square foot
- Must be supplemented with a separate DIC policy for full protection
FAIR Plan + DIC Policy Combination
Pros:
- Approximates full admitted-market coverage in scope
- Accessible even in high-fire-risk zones where admitted carriers won’t write policies
Cons:
- Typically costs 1.5x to 2.5x the equivalent admitted market policy
- Requires managing two separate policies and carriers
- Total annual cost for a $1M dwelling in a high-fire zone can reach $9,500 to $15,000
Frequently Asked Questions About Fire Insurance in Valencia and Saugus
How much is fire insurance for a typical home in Valencia in 2026?
For homes with dwelling values in the $500K to $800K range in suburban LA areas like Valencia’s flatlands, premiums typically run $1,400 to $2,800 per year with admitted market carriers, per 2026 California insurance market data. Your exact rate depends on your fire hazard zone classification, construction type, and distance to fire protection.
What does fire insurance cost for a luxury home in Saugus?
For upscale homes in Saugus with dwelling values between $1M and $2M in a moderate Fire Hazard Severity Zone, expect $3,500 to $8,500 annually, per 2026 insurance industry estimates. Hillside properties closer to canyon areas may fall on the higher end of that range.
Does the California FAIR Plan cover luxury homes in the Santa Clarita Valley?
The FAIR Plan caps residential coverage at $3 million, per current policy limits. For many luxury properties in Valencia and Saugus, this may cover the rebuild. However, the FAIR Plan only covers fire losses, so you’ll need a separate DIC policy for comprehensive protection.
How much does a FAIR Plan plus DIC policy cost?
For a $1M dwelling in a high-fire zone, the combined FAIR Plan plus DIC cost can reach $9,500 to $15,000 annually, per 2026 estimates. This typically runs 1.5x to 2.5x the cost of equivalent admitted market coverage.
Are Valencia flatland homes cheaper to insure than hillside homes?
Yes. Most Valencia and Saugus flatland areas are not classified as Very High Fire Hazard Severity Zones, which generally keeps premiums more moderate. Hillside neighborhoods like portions of Tesoro del Valle can carry higher risk classifications due to elevation and brush proximity.
What carriers specialize in luxury home fire insurance in California?
Chubb, PURE Insurance, AIG Private Client Group, and Cincinnati Insurance are among the carriers offering high-net-worth coverage with benefits like guaranteed replacement cost and concierge claims service. These tend to cost more upfront but provide superior protection for high-value properties.
How much has the California FAIR Plan grown recently?
The number of FAIR Plan residential policies increased 151% between September 2022 and March 2026, per California Department of Insurance data. Total risk exposure jumped 234% to $700 billion during that same period.
Can fire-resistant construction lower my premium in Valencia?
Yes. Fire-resistant construction such as stucco or brick can reduce premiums to $1,000 to $2,200 per year versus $1,500 to $3,000 for standard wood frame, per 2026 California insurance data. Defensible space and sprinkler systems can earn an additional 10% to 25% discount.
Should I get an insurance quote before making an offer on a Valencia or Saugus home?
Absolutely. Your fire insurance premium is a significant component of your total monthly carrying cost, especially at the luxury level. Getting a quote before writing an offer prevents budget surprises during escrow and gives you negotiating leverage.
What rebuild cost should I use when calculating my coverage needs?
For upscale homes in the Santa Clarita area, rebuild costs typically run $475 to $700 per square foot, and $650 to $1,100+ per square foot for custom luxury construction, according to Claims Journal data from July 2026. A 4,000 square foot luxury home could cost $1.9M to $2.8M to rebuild.
The Bottom Line on Fire Insurance for Valencia and Saugus Luxury Homes
Fire insurance is no longer a line item you can estimate and move on from. In 2026, it’s a defining factor in your total cost of ownership, and it varies dramatically based on where in Valencia or Saugus you buy, what your home is built from, and which coverage structure you choose. I live in this community, I work in this market every day, and I hear the conversations happening at the local level about how these costs are reshaping buying decisions.
If you’re shopping for a luxury home in Valencia, Saugus, Stevenson Ranch, or Newhall and want someone who understands both the real estate and the insurance landscape, I’d be glad to walk through the numbers with you. Give me a call at 213-598-8205 or visit timothyatwood.com to connect directly. Let’s make sure your next home is one you can protect and afford to keep.
—
Timothy Atwood | Santa Clarita Valley Real Estate 📞 213-598-8205 🌐 timothyatwood.com Serving Valencia, Saugus, Stevenson Ranch, Newhall, and the greater Santa Clarita Valley